
Asset Finance, Explained.
Hire purchase, finance leases and operating leases for vans, machinery and equipment, and how to choose between them. Then tell us what you need.
For UK limited companies. Free to use, no obligation, and no credit check to make an enquiry.
Or read the guide first- Asset finance for UK businesses
- £40.3bnnew business in 2025, up 1%
- Lent to smaller businesses
- £24.4bnin 2025, up 4% for a fifth year of growth
- Of smaller businesses
- 13%used leasing or hire purchase in mid 2025
- Commercial vehicles
- £10.8bnfinanced in 2025, the largest single type
Sources: Finance & Leasing Association (5 March 2026) and British Business Bank, Small Business Finance Markets 2025/26 (17 March 2026).
What Is Asset Finance?
Asset finance lets a business get vehicles, machinery or equipment without paying the full price upfront. You either buy the asset in instalments and own it at the end (hire purchase), or pay to use it for a fixed period (a finance or operating lease).
It is one of the most used kinds of business finance: UK businesses took out £40.3bn of new asset finance in 2025, according to the Finance & Leasing Association, and £24.4bn of that went to smaller businesses.
Types Of Asset Finance
Each spreads the cost so you avoid paying it all upfront. The difference is who owns the asset and who looks after it.
Hire purchase
You pay fixed instalments plus interest and own the asset at the end. If you fall behind, the lender can take the asset back.
Finance lease
The provider buys the asset and leases it to you for monthly payments. You insure and maintain it.
Operating lease
You rent the asset for a set period and may be able to upgrade during it. The provider maintains it.
Source: British Business Bank, Making business finance work for you.
Is Asset Finance A Loan?
Not quite. The British Business Bank groups it with debt finance, but it is tied to a specific asset and secured on that asset, rather than being cash you can spend on anything.
- What it pays for
- Asset finance pays for one asset. A business loan gives you cash to use across the business.
- What secures it
- The asset itself. If you do not keep up payments, the lender can recover it. A loan may be secured on other assets, or on nothing.
- Cash flow
- Monthly payments let you use the asset while it earns its keep, without a large upfront cost.
- Who owns it
- With hire purchase you own the asset at the end. With a lease the provider owns it and you pay to use it.
Source: British Business Bank, Making business finance work for you.
What Can You Finance?
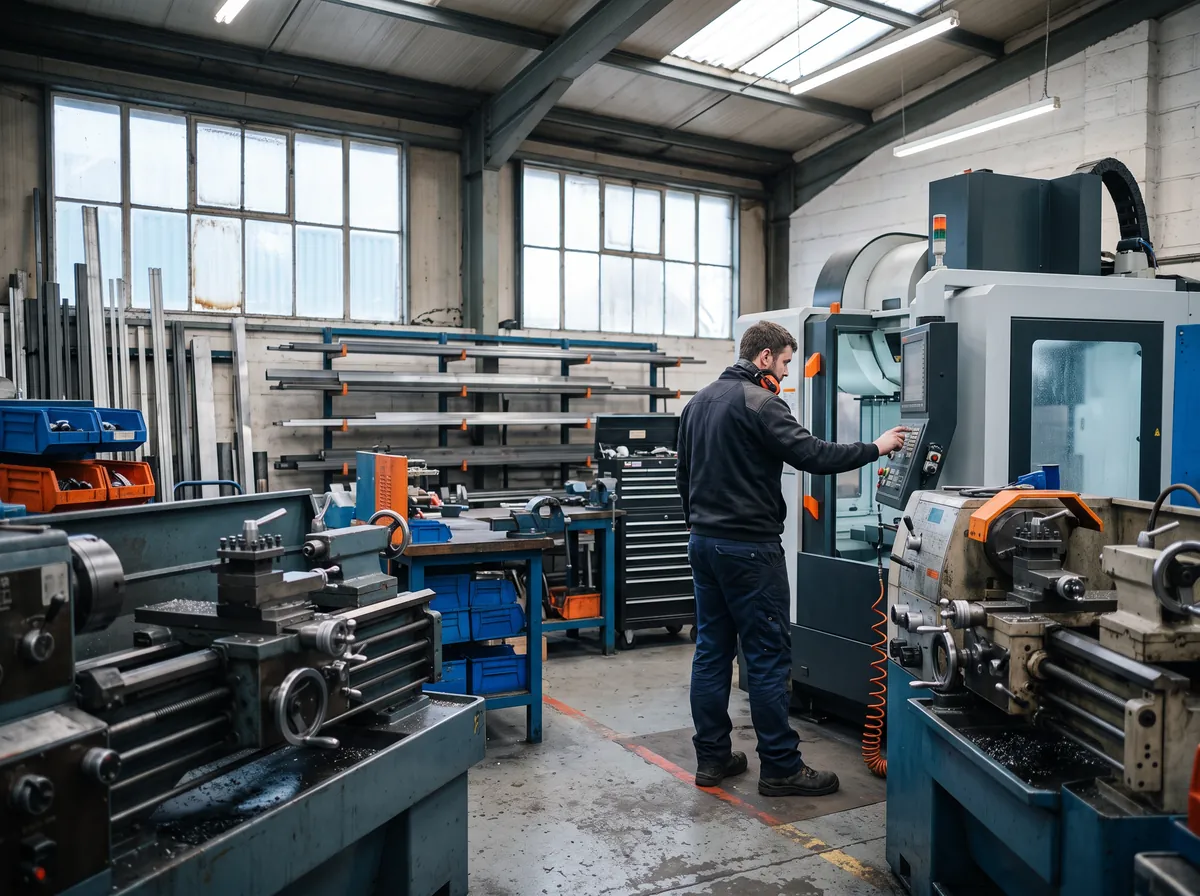
Almost anything with a resale value that the business uses to earn money. Vehicles and machinery make up the biggest share.
- Vans, trucks and other commercial vehicles
- £10.8bn of new finance in 2025, the largest single category in FLA figures.
- Plant and machinery
- £7.8bn in 2025, up 3%: from forklifts and diggers to production lines.
- IT and office equipment
- Computers, phones and point-of-sale kit, often on operating leases so you can upgrade.
- Specialist equipment
- Catering, medical, agricultural and workshop kit, depending on the lender.
Source: Finance & Leasing Association, asset finance new business 2025 (5 March 2026).
More Types Of Asset Finance
Beyond hire purchase and leasing, these are the terms you will meet when comparing equipment finance.
- Equipment finance
- Asset finance used for machinery, tools and other equipment, usually through hire purchase or a lease.
- Contract hire
- A long-term rental, mostly used for vehicles. You pay a fixed monthly rental and hand the vehicle back at the end.
- Asset refinance
- Raising cash against equipment or vehicles your business already owns.
- Sale and leaseback
- Selling an asset you own to a finance provider, then leasing it back so you keep using it.
- Hard and soft assets
- Hard assets, such as vans and machinery, keep a resale value. Soft assets, such as IT and software, lose value faster, so lenders can be more cautious with them.
How Switchable Works
Tell us what your company wants to finance and one business finance broker partner will get in touch about hire purchase and leasing options.
Tell us what you need
How much, what it is for and a few details about your company. It takes about two minutes.
We check the basics
We look your company up on Companies House and check it fits what our broker partners can help with.
A broker gets in touch
One business finance broker partner contacts you to talk through the options for your company.
You decide
There is no obligation to go ahead. Ask about any fees before you agree to anything.
Who our broker partners can help
- A UK limited company
- Trading for at least 12 months
- Turnover of £100,000 a year or more
- A director who owns their home
Find Finance That Fits Your Company
Tell us how much you need and one business finance broker partner will be in touch. Free, no obligation.
Questions To Ask Before You Sign
Asset finance agreements differ more than they first look. These questions separate a good deal from an expensive one.
- Who owns it at the end? With hire purchase you do; with a lease you usually return it or extend.
- Who maintains and insures it? You do on a finance lease; the provider does on an operating lease.
- What is the total cost? Add every payment, the deposit and any final or option fee.
- What if you want out early? Ask about settlement and early termination charges.
- Can you upgrade? Useful for kit that dates quickly, such as IT.
- What happens if you miss a payment? On hire purchase the lender may take the asset back.
Source: definitions from the British Business Bank guide.
Asset Finance Questions, Answered.
Is asset finance easy to get?
It can be easier than an unsecured loan, because the asset itself secures the finance. Lenders still check your trading history, accounts and credit record, and assets that hold their value, such as vans and machinery, are easier to finance than IT or software.
What interest rates apply to asset finance?
There is no standard rate. It depends on the lender, the asset, the term, any deposit and your credit record, and it can be fixed or variable. Ask for the total amount payable, not just the monthly figure.
What is equipment finance?
Asset finance for machinery, tools and other equipment. It usually works through hire purchase, so you own the equipment at the end, or a lease, so you pay to use it.
How common is asset finance?
Very. 13% of smaller UK businesses used leasing or hire purchase in the third quarter of 2025, according to the British Business Bank, and smaller businesses took out £24.4bn of new asset finance in 2025.
What is the difference between hire purchase and leasing?
With hire purchase you pay fixed instalments plus interest and own the asset at the end. With a lease you pay to use it for a set period. On a finance lease you insure and maintain it; on an operating lease the provider maintains it.
Can I finance used equipment or vehicles?
Often, yes, though terms depend on the lender and the age of the asset. A broker can tell you which lenders take used kit.
Can you help sole traders?
Not at the moment. Our broker partners work with UK limited companies that have traded for at least 12 months, turn over £100,000 a year or more and have a director who owns their home. For other options, the British Business Bank has free, impartial guidance on business finance.
Is business finance regulated?
Lending to a limited company is not regulated consumer credit. The FCA says loans to companies fall outside consumer credit rules, and the same goes for broking them. That makes it worth reading every agreement closely, including any personal guarantee.
Does Switchable charge me?
No. Our service is free to use: we are paid by the broker partners we introduce you to. A broker may charge its own fee for arranging finance, so ask about fees before you agree to anything.
Will making an enquiry affect my credit score?
Telling us what you need does not involve a credit check. A broker or lender may run checks later if you decide to apply, so ask them how they check before you agree.
Finance Your Next Van, Machine Or Kit.
Tell us what you need and a business finance broker partner will be in touch about the options. Free, no obligation.